
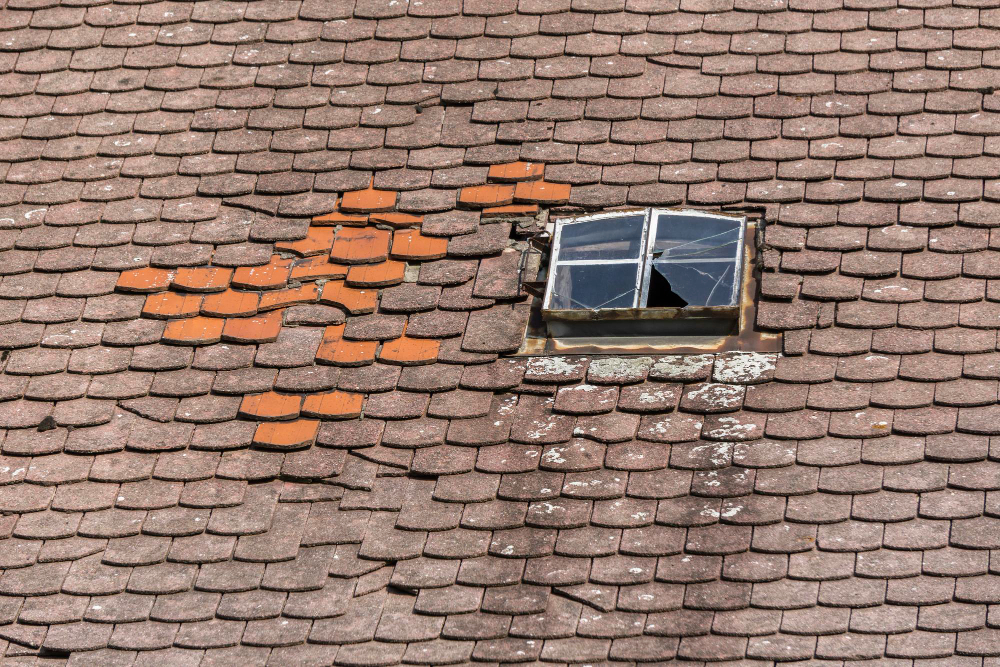
Does home insurance cover roof leaks and damage?
Most home insurance covers roof leaks and damage caused by a sudden event, a storm, a fire, a falling tree. It usually doesn't cover damage from wear and tear or poor maintenance. Which side of that line you're on decides almost everything else.
What does home insurance cover for roof leaks and damage?
Roof cover isn't sold separately. It sits inside your buildings insurance policy, which protects your roof's structure and the rest of your home, walls and floors included, against sudden, unforeseen events.
Put plainly: does home insurance cover roof leaks and damage? Usually, yes, when a storm, a fire or another sudden event is the cause.
What's covered, and what isn't
This distinction between a tree falling naturally and being actively felled or lopped is a real exclusion category in UK policies. A published Ombudsman decision discusses this exact clause: since the tree had already fallen and only needed removing, the exclusion didn't apply, and the Ombudsman sided with the customer.
One test decides almost every claim
Was the damage sudden and unexpected, or the result of gradual deterioration? Most home insurance policies expect a well-kept roof, and reading your own home insurance policy carefully is the only way to know your exact terms. Missing tiles left unreplaced or visible moss build-up make a claim harder to win, whatever caused the damage.
If water is coming into your home right now, the reason behind it matters less than what you do in the next few minutes. Skip ahead to what to do the moment you spot a roof leak.
A leaking roof often damages more than the roof itself. Buildings insurance covers the structure; contents insurance covers what's inside. Water damage often triggers both claims at once, if a leak ruins a carpet or damages furniture as well as the roof.
Insurance companies generally treat these as separate lines on the same policy documents, so check both sections before assuming you're covered. rivr's guide to what buildings insurance covers sets out that split in more detail, since the same principle applies to your whole policy.
Does your roof type affect the risk of leaks and damage?
Yes, significantly, and it changes what insurers expect from you.
Flat roofs
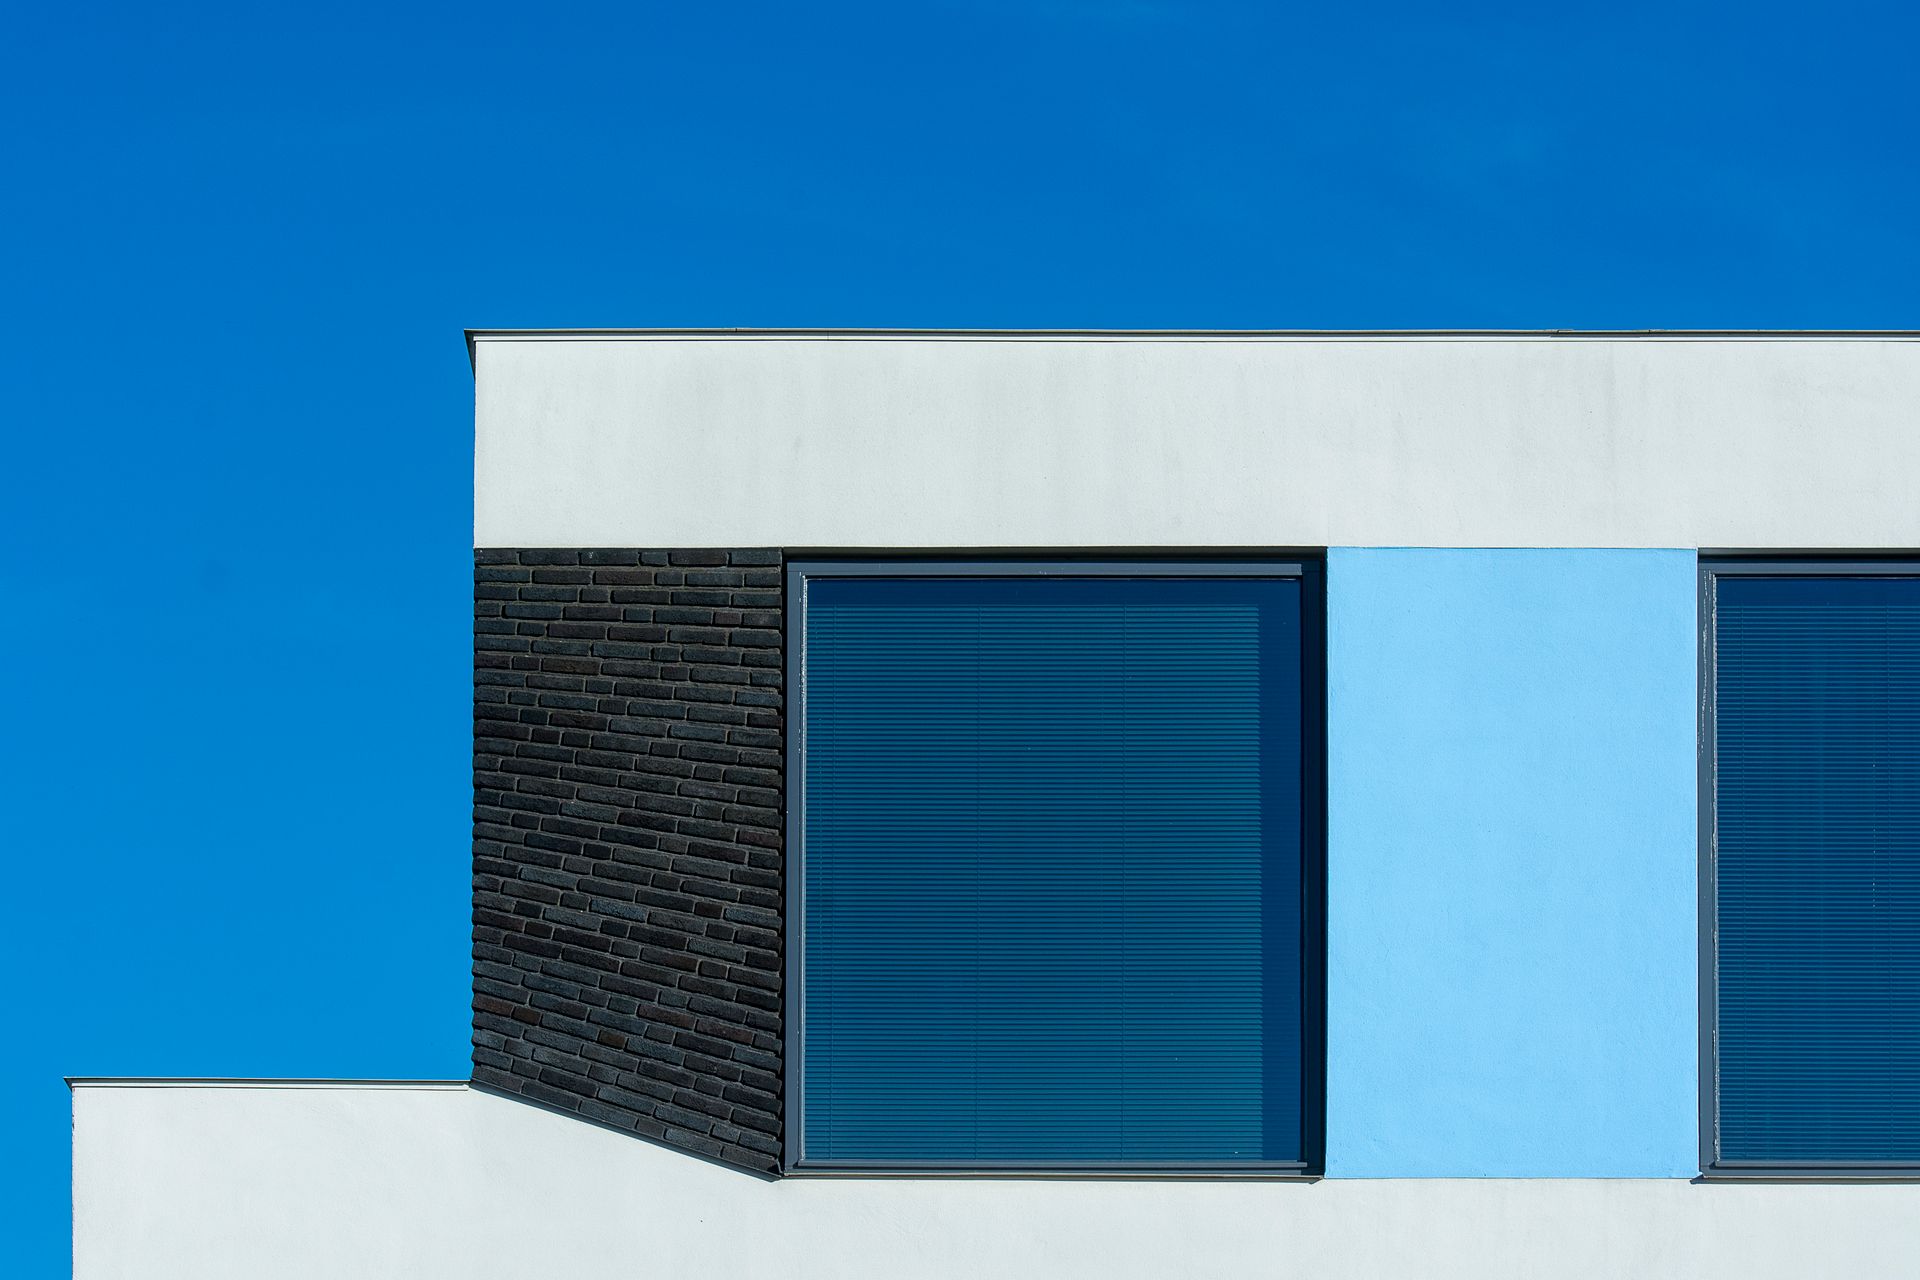
Flat roofs carry the highest risk of any category. Some home insurance policies apply higher excesses or extra conditions where flat roofing covers a large share of the structure, so it's worth reading your insurance policy closely on this point. Keeping a flat roof well maintained matters more than on a pitched roof, since insurers scrutinise upkeep closely when one leaks.
Thatched roofs
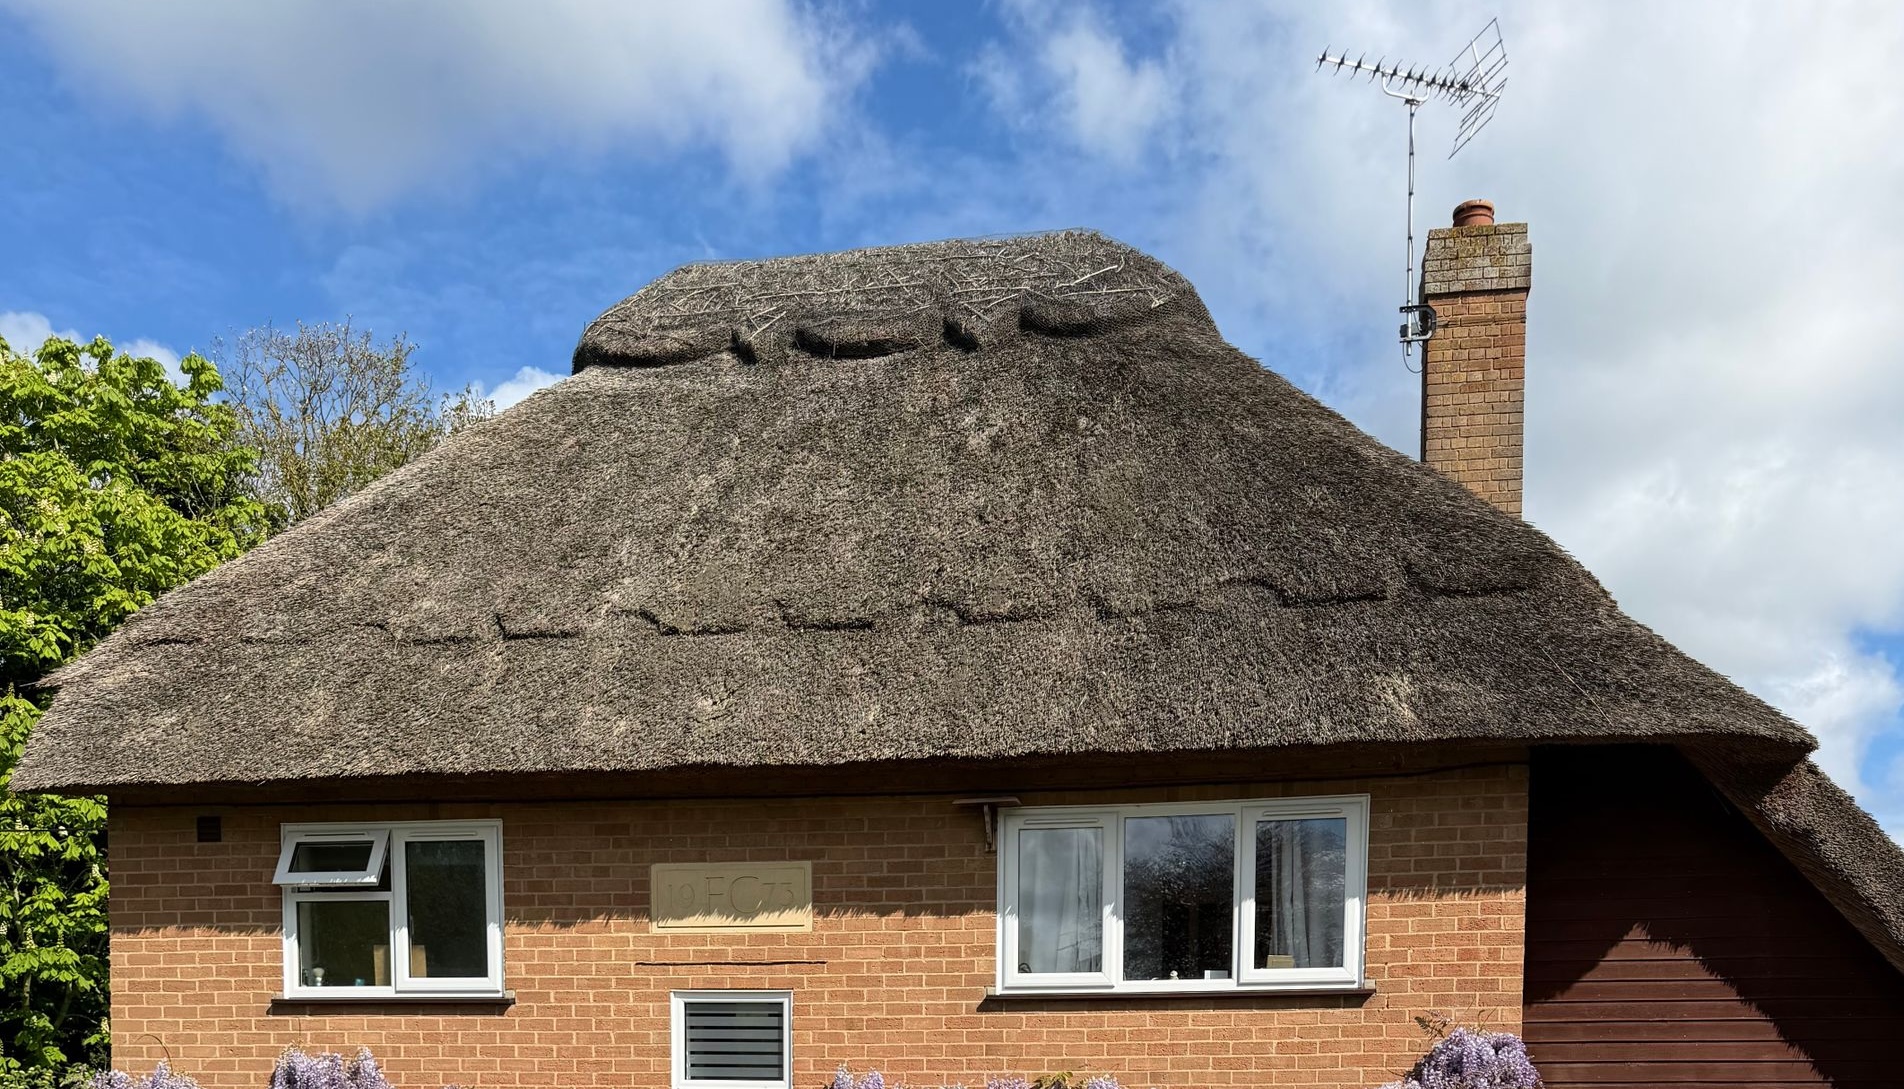
Thatched roofs need specialist cover, mainly because of fire risk; leak risk is a secondary concern. They also carry their own maintenance demands, and premiums reflect the higher repair costs and specialist materials involved. A policy built for standard tiled roofs typically won't extend to thatch or other non-standard roofing materials without a tailored arrangement.
Standard tiled and slated roofs
These are usually covered without extra conditions. Unusual materials may still need specialist underwriting, so check your policy documents. Don't assume a match applies.
Whatever kind of roof you have, the same question decides most cases: was the damage sudden and accidental, or the result of age and neglect?
What causes roof leaks and roof damage?
If a claim is turned down, it's usually because the insurer believes the damage could have been prevented, or falls outside what the policy covers.
Storm damage
High wind, heavy rain, snow or hail can lift tiles, break ridge tiles, damage flashing, or dislodge sections of a flat roof.
What insurers mean by "storm"
The ABI's guidance defines a storm as violent weather involving one or more of: gusts of at least 55mph, rainfall of at least 25mm per hour, snow of at least 30cm in 24 hours, or hail intense enough to damage hard surfaces or break glass.
These numbers are guidance. A claim can still succeed even when recorded wind speeds fall short of them, if local conditions were severe enough, more on that in the Ombudsman section below.
How disputes get assessed
When a claim is declined, the Financial Ombudsman Service looks at whether extreme weather actually occurred at the property, whether the damage is consistent with that kind of impact, and whether wear and tear can genuinely be ruled out as the real explanation. Local weather conditions and a clear inspection report matter because of exactly this test.
Fire or explosion
Roof damage from fire is usually covered, including full replacement if necessary, and the same generally applies to an explosion.
Falling trees and debris
A falling tree or branch, or debris dislodged in bad weather, is normally covered when it damages the roof structure. Trimming nearby trees and any branches that overhang your roof reduces this risk before it becomes something you need to claim for.
Vandalism and malicious damage
Deliberate damage, broken tiles, damaged timbers, is generally covered by home insurance. A police crime reference number strengthens your position.
Wear and tear and gradual deterioration
Tiles slip, flashing corrodes, and aging shingles are one of the most common causes of a roof leak. None of it happens overnight.
This slow decline is what insurers mean by wear and tear, and standard policies don't cover it. Insurance is built for sudden events. Ordinary ageing isn't one of them.
Poor workmanship from a previous repair can cause the same symptoms as an event that would otherwise be covered, and can lead an insurer to the wrong conclusion about the actual cause. It's one reason insurers send a surveyor. Accepting a claim at face value risks paying for something the policy was never designed to cover.
Accidental damage, if included
Some policies add optional accidental damage cover, for things like putting a foot through the ceiling during DIY or dropping equipment on a flat roof. Not every plan includes this, so check before assuming your home insurance policy does.
How to spot a roof leak early
Catching a leaking roof early limits the damage and puts you in a stronger position if you need to claim later. Watch for:
- Water stains on ceilings or walls
- Dripping water inside the house, especially on a rainy day
- Mould or damp patches that appear without an obvious cause
- Missing or visibly displaced roof tiles
- Sagging sections of roof timber
If you notice any of these, the roof may be leaking even if you can't see where water is getting in. Don't wait to investigate. A small, unnoticed leaky roof problem can lead to serious damage that's far more expensive to put right, and an insurer is less likely to cover damage it decides was allowed to develop over time.
What to do the moment you spot a roof leak
- Contain the water. Place buckets under the drip, and move valuables and furniture away from the affected area to prevent further damage.
- Photograph the damage as it appears, before you start any repairs.
- A tarp over an accessible area can help make things safe for now, but only if it's safe to do so, avoid this on a steep or wet roof.
- Contact your insurer promptly. Many insurance policies expect early reporting, and delay can weaken your claim even when the underlying cause would otherwise be covered.
- Get a professional inspection. A roofer's written report on the likely cause is some of the strongest evidence you can provide, and a crucial step if the claim is ever disputed.
How much do roof repairs cost?
Indicative costs only, updated September 2026. Prices vary by roof type, access, extent of damage, and material matching.
Sources: Checkatrade, MyJobQuote.
Types of roof repairs
Not every job is the same size or price. Some examples of the most common repairs:
Broken or missing roof tiles
Weather, falling objects and normal wear all produce damaged tiles that need replacing, usually just for the affected area, sparing the rest of the roof.
Damaged flashing
Flashing is the metal sealing around chimneys, vents and other roof penetrations. Once it corrodes or lifts, water finds its way in at exactly that point.
Roof felt repairs
Roof felt is the waterproof layer beneath the visible roofing material. A puncture here can cause a leak with no obvious external sign.
Fascia and soffit repairs
Fascia and soffits seal the roof at the eaves. Both can rot or come loose over time, and a neglected one can lead to rot spreading into the roof timbers behind it, which is why fixing them early is cheaper than waiting.
Sagging roof repairs
A visibly sagging section is a sign of structural damage, and typically needs a surveyor's assessment before repair.
How to prevent roof leaks and damage
Small problems left alone tend to lead to expensive ones. Regularly inspect the roof and most issues get caught while they're still cheap to fix.
- Check roof tiles regularly, and replace any that are damaged or missing before water gets in.
- Blocked gutters are one of the most preventable causes of a leak, so keep your guttering clear.
- Overhanging branches and nearby trees are worth trimming back, since falling debris is a common cause of a leaking roof and structural damage.
- Skylight seals should stay intact. Check them for gaps that let water infiltrate around the frame.
- Flat roofs need closer attention than pitched ones, check the felt or coating for cracks, tears or blisters.
- An annual inspection catches most of this early, and it's worth doing again after any severe weather.
Seasonal roof risk across the UK
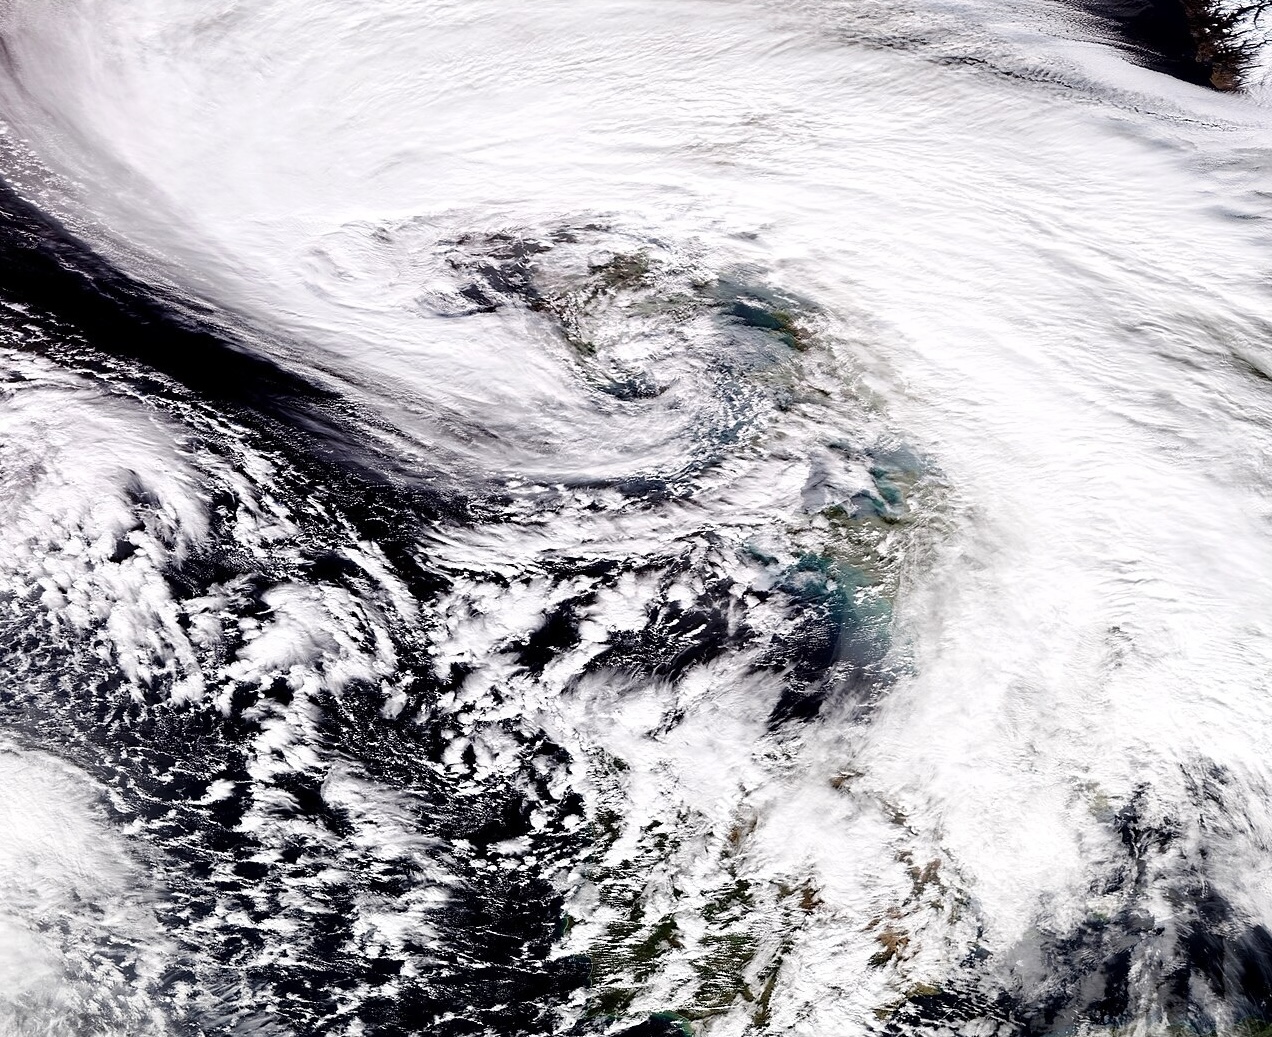
Satellite image of Storm Chandra, photographed by By NASA Worldview, January 27, 2026.
UK weather conditions mean the risk isn't constant across the year.
Autumn is peak season for weather-related roof damage. Heavy rain and strong winds combine with leaves and debris blocking gutters. Storm Amy, which hit north-western parts of the UK on 3–4 October 2025, brought gusts exceeding 92mph, an unusually severe event for October, according to the Met Office.
Winter brings snow, ice and heavy rainfall. Storm Chandra, named by the Met Office in late January 2026, produced exceptional rainfall totals, including a record January daily fall of 115.1mm at White Barrow in Devon, tipping already-saturated ground into flooding across Ireland, Northern Ireland and England.
Spring often exposes weaknesses that built up over winter, making it a sensible time for repairs.
Summer heat can degrade roofing materials, leaving them more vulnerable when the next bad weather arrives.
How to make a strong claim
Insurers want clear proof before they'll pay out. Before starting urgent repairs, gather:
- Photos and video of the damage and any affected areas inside the house
- An inspection report from a professional roofer, where possible
- Maintenance records showing the roof has been kept in good condition
- Local weather details covering the date of the damage
A home insurance claim for roof damage follows a similar process whether the cause was a storm, a fire, or something else covered by your policy. Then follow the process:
- Contact your insurer as soon as you notice damage.
- Arrange only the emergency repairs needed to stop things getting worse, and keep every receipt.
- Submit photos, inspection reports and any relevant policy documents.
- Expect a loss adjuster, sent by the insurer, to inspect the damage and confirm the cause.
A detailed, prompt submission materially improves the odds of a successful claim for a storm or other sudden event.
What to do if your roof insurance claim is rejected
- Ask for a written explanation. The usual grounds are a poorly maintained roof, pre-existing or gradual damage, or an unmet policy condition.
- Get a second opinion from a professional roofer, and gather any further inspection reports or receipts for recent repairs, anything that strengthens your position.
- If you still disagree, put it in writing as a formal complaint. Insurers generally have eight weeks to respond, and you have six months after their final response to take it to the Financial Ombudsman Service.
Insurers must justify a decline with evidence, an inspection report, photographs, or an expert assessment. A rejection can't be based on assumption alone.
How the Financial Ombudsman decides roof storm disputes
Storm damage to UK homes reached £244 million in 2025, a 32% increase on the year before, with the average storm payout rising to £2,450. At that scale, disputes are common: buildings insurance complaints to the Financial Ombudsman had a 38% uphold rate in the most recently published quarter, October to December 2025.
The Ombudsman's published decisions show what actually happens once a dispute goes to a formal review, and the outcome isn't always predictable from the insurer's initial reasoning.
When the insurer's own evidence wasn't good enough
In one dispute, an insurer declined a customer's claim, and two Ombudsman investigators initially agreed the decline was reasonable. The Ombudsman's own review then overturned it, because the insurer hadn't produced surveyor evidence showing the natural breakdown of the roofing materials or the property's prior condition.
The dispute was settled in the customer's favour, plus £150 compensation for the delay, in one published Ombudsman decision.
When recorded wind speeds looked too low
In a separate published example, an insurer declined a claim because recorded wind speeds at the nearest weather station hadn't reached its stated threshold of around 55 to 63mph. The Ombudsman still upheld the customer's complaint. Damage can occur below that speed: a localised gust near a specific property can be stronger than a distant weather station's reading, and the layout of nearby buildings can create unusual wind conditions of their own.
When the decline was upheld
Not every dispute goes the customer's way. In another published decision, a flat roof lifted during high winds and let water into the home, and the Ombudsman agreed storm conditions had occurred and caused damage consistent with a storm.
But photos showed the roof was already cracked and its gutters clogged with vegetation before the storm hit, evidence the insurer's wear-and-tear exclusion applied fairly. The decline stood.
The pattern across all three: the Ombudsman weighs the quality of the insurer's own evidence as closely as it weighs yours. A decline built on a genuine, well-evidenced inspection tends to stand. One built on a distant weather reading alone doesn't always, and damage that looked uncovered at first can still end up covered once the full picture is examined.
Will making a roof claim increase your home insurance premium?
Often, yes, and having a claim on record costs more even when premiums are already rising for everyone. In a 2023 study, Consumer Intelligence's UK Home Insurance Price Index found that, over the 12 months to October 2023, homeowners with a buildings claim saw quoted premiums rise by 40.7%, against 35.7% for those with no claims at all. Water-related claims saw the steepest rise, at 42.8%.
That gap, roughly five percentage points for a buildings claim, held even during a period when every homeowner's premium was climbing for unrelated reasons, rising material and repair costs, more extreme weather, and general market inflation. A claim doesn't just track the market rate, it adds to it.
More recent ABI figures show the pressure behind this hasn't eased: insurers paid out a record £6.1 billion in property claims in 2025, and the average home insurance claim rose 15% to £6,000.
Renting or owning: who's responsible for roof repairs?
If you're renting, your landlord is responsible for the building, including the roof and its buildings insurance. Their insurance company won't cover your belongings, that's what your own contents insurance is for. If a leak damages your possessions, you can claim under your own policy regardless of whose responsibility the roof itself is.
If you own the property, you (or your freeholder, in a shared building) are responsible for maintaining the roof and holding buildings insurance. If you're a leaseholder, check your lease documents for exactly who's responsible, it's usually the freeholder.
High-value and period home roofs: what's different?
Larger or older properties often use materials and construction that change both the cost of a repair and the process for getting one approved.
Materials and specialist trades
Welsh slate, the traditional choice for period and listed roofs, costs £140 to £180 per m² installed, against £70 to £100 for a synthetic equivalent, according to MyBuilder's cost data. Lead and thatch work needs tradespeople who are rarer and often booked months ahead, so a generic repair quote rarely reflects what these materials actually cost to source and lay.
Listed building consent
On a listed building, anything beyond minor patching usually needs consent. Local planning authorities, who administer listed building consent in England, commonly apply a threshold of 50% of one roof slope: a patch repair below that, in matching materials, typically doesn't need consent.
A full re-covering, or patching beyond that threshold, does, and the replacement materials will usually need to match the original like-for-like. Starting work without consent on a listed property is itself a criminal offence under Section 9 of the Planning (Listed Buildings and Conservation Areas) Act 1990, separate from any insurance question.
Lead theft
Lead theft is a recognised risk specific to period roofs, distinct from ordinary storm or vandalism damage. Historic England's guidance on metal theft is written primarily for places of worship, though it states its principles apply to historic buildings generally. It treats like-for-like replacement as the default, since swapping stolen lead for another material can itself affect a building's listed status.
None of this changes the core test running through this guide, sudden damage is still what a policy responds to. It changes the scale of what's at stake and, on a listed property, the process for fixing it.
How rivr's cover reflects this
rivr's own buildings cover works on that same basis: covered unless specifically excluded, with no list of named perils to match your claim against. Its Extended Replacement Cover extension pays the full cost of rebuilding or repairing even above your sum insured, provided there's an independent Chartered Surveyor valuation less than three years old, authorised by rivr. One exception matters here: Grade 1 and Grade A listed buildings are excluded from this specific extension.
Non-routine work, including a major re-roofing project, is covered up to a £100,000 contract value, provided it's declared before the total cost passes that figure. For listed properties specifically, rivr's specialist listed buildings cover is built around exactly these requirements.
Checklist: keeping your roof insured
For empty properties, specialist unoccupied building insurance may be needed, since standard cover often restricts claims once a house has been empty for a set period.

Read more
Frequently asked questions
Most rejections come down to cause. Insurers decline roof claims when they believe the underlying cause was wear and tear, gradual deterioration, or poor maintenance. A sudden insured event is what a policy is actually designed to pay out for.
The Financial Ombudsman Service checks whether severe weather occurred, whether the damage matches that kind of impact, and whether it was the main cause.
Sometimes, usually only if full replacement is needed to fix insured damage. Buildings policies generally aim to put you back in the position you were in just before the damage happened, through repair, replacement, or a cash settlement. If the cause is judged to be gradual wear and tear, a full replacement is unlikely to be treated as covered.
The ABI's definition involves one or more of: 55mph gusts, 25mm of rain per hour, 30cm of snow in 24 hours, or damaging hail. Many policies don't define it precisely, so insurers and the Ombudsman also weigh local weather conditions and whether the damage is consistent with that kind of event, even where recorded speeds fall just short of the guidance figure.
Dated photos or video, a roofer or surveyor's report on the likely cause, any maintenance or repair records, and local weather details around the date of the damage caused. If a claim is disputed, the Financial Ombudsman Service typically weighs local conditions, the property's condition, and whether the damage is consistent with what's claimed.
Ask your insurer for a written explanation and the evidence behind it, an inspection report, for example. If you disagree, make a formal complaint, insurers generally have eight weeks to respond. After their final response, you have six months to take it to the Financial Ombudsman Service.
Sometimes. If snow or ice causes sudden, identifiable damage, tiles dislodged, a structural failure, and your policy covers that peril, it's likely to be covered. Gradual deterioration and general wear are commonly excluded, so check your insurance policy wording.
Contact your insurance company straight away and describe the leak and its likely cause in as much detail as you can. Take photos, gather any relevant weather conditions data, and keep records of past maintenance. Flat roofs sometimes need specialist cover, so confirm what your specific insurance policy includes.
Yes, if a storm causes the leak, rivr's buildings insurance covers the roof repair and resulting internal damage as standard, provided the roof had been properly maintained. Leaks from wear and tear or ageing materials aren't covered. Check your policy documents and photograph the damage before you claim.
No. Flat roofs are usually assessed under the same sudden-versus-gradual rule as any other roof, but they're inspected more closely because the risk is higher. A well-documented, promptly reported leak that a storm or similar event actually caused is treated the same as on any other roof type, one linked to age or lack of maintenance generally isn't.
Your landlord is generally responsible for major structural repairs, including the roof, and for holding buildings insurance on it. Your own contents insurance covers your belongings; your landlord's buildings insurance covers the building itself. You may still be able to claim for damaged items depending on your own cover and what caused the damage.
rivr's Property Emergency cover covers roof damage where internal damage has been or is likely to be caused, arranging a contractor for a temporary repair. Permanent repairs sit outside this cover, and it doesn't apply if the home has been unoccupied for more than 30 consecutive days.
